The algo trading Discord with a backtesting bot
Most trading Discord servers sell signals. This one is a community for systematic traders and Python quants who would rather test an idea than follow one. Describe a strategy in a sentence, and Fold, our bot, backtests it with the Manifold-BT engine right in the channel.
Run a backtest from Discord
Fold is a backtesting bot for Discord. It does not guess at a result or summarise someone else's: every reply is a fresh run of the same engine you would install with pip.
Describe the strategy
plain EnglishType /backtest and write the idea the way you would say it: the rule, the market, the interval, the start date. Anything you leave out gets a sensible default, and the reply tells you which one it picked.
The engine runs it
manifoldbtThe sentence becomes a Manifold-BT strategy, the same expression DSL you would write in Python, and the Rust engine runs it against stored market history. Nothing is estimated, the numbers come from an actual backtest.
You see what was tested
no black boxThe reply lists CAGR, Sharpe, max drawdown, trade count and fees, then the exact signals, position rule, market, interval and window that produced them, with an equity curve attached.
Real replies from the server
Two backtests run in the server, captured as Fold posted them. The numbers are what the engine returned, warnings included.
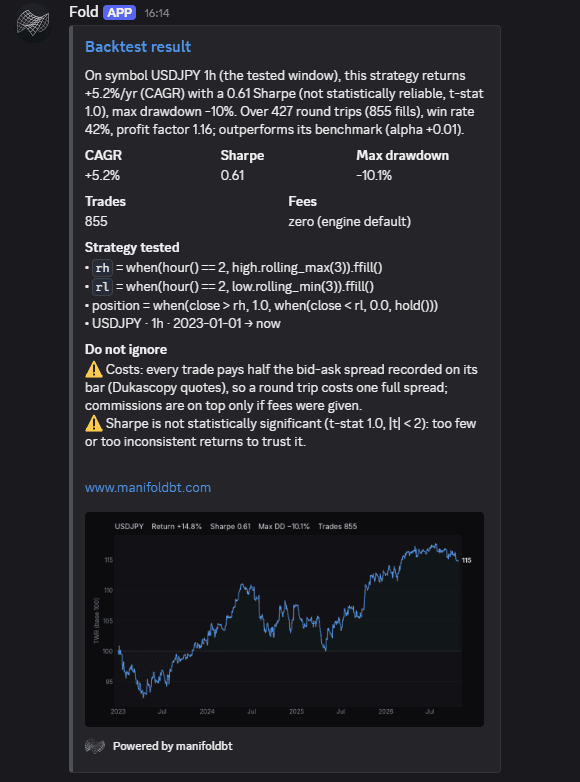
Long above the high of the three bars to 02:00, flat below their low. Every fill pays half the recorded spread, and the reply still flags a Sharpe too weak to trust.
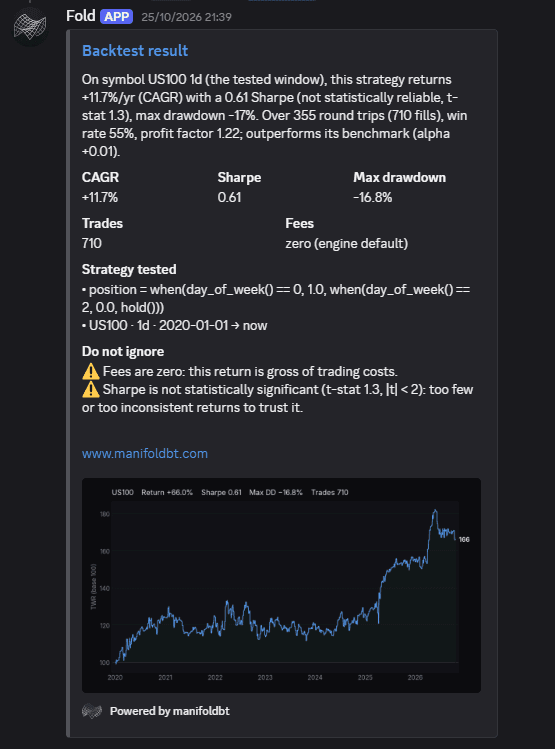
A calendar effect since 2020. The equity curve looks fine, and the reply says why that is not enough: no fees were set, and the t-stat is 1.3.
Three commands
Slash commands only, so the bot stays quiet until someone asks it for something.
/backtestTest a strategy described in one sentence. Long and short rules, equal-weight portfolios across several markets, pair trades on a spread, fees in basis points or as a preset.
/symbolsEvery market the bot can test, grouped by exchange and asset class, so you know what to ask for before you ask.
/helpCommands, worked examples, the markets covered and how much of the server's daily backtest quota is left.
/backtest RSI 30/70 on BTC 1h since 2023

/backtest EMA 20/50 crossover on XAUUSD 4h, long only

/backtest Breakout on EURUSD 1h: long above the 50-bar high,
          exit below the 20-bar low, 2 bps fees

/backtest Equal-weight RSI 30/70 on COPPER, NATGAS and COFFEE,
          4h since 2019

/backtest Pair trade NQ vs ES 4h: z-score of the spread over
          20 bars, enter at ±2, exit at 0
The strategy is written in the Manifold-BT expression DSL behind the scenes, and the reply shows it, so you can take it straight into Python.
Built to show you what could be wrong
A Discord backtesting bot that only ever posts nice equity curves would do more harm than good. Fold is built the other way round.
Warnings are never hidden
do not ignoreWhen the engine flags something about a run, the reply says so in a field of its own. A backtest that looks good and carries a warning is shown with the warning, not without it.
Real costs on every market
spreadForex, indices and commodities are filled at the bid-ask spread recorded in the data, and crypto pays the fees you specify or a Binance preset. Leave fees at zero and the reply tells you the return is gross of costs.
A research tool, not advice
historyEvery result is a historical simulation. Fold does not place orders, follow a portfolio or send alerts, and it never tells anyone what to buy.
A quant community, not a chat room
The bot is the quick way in. The conversations are where most of the value is: people who backtest in Python, comparing notes on method rather than on positions.
Strategy research
Testing an idea before it eats a weekend: how to frame the rule, which window to use, why a result that looks great usually is not.
Engine and API help
Questions about the expression DSL, execution settings, data stores and error messages, answered by the people who build the engine.
Coming from vectorbt
Porting a notebook, mapping familiar concepts to Manifold-BT, and checking that the two give the same answer on the same strategy.
Releases and roadmap
Early notice on what ships next, bug reports that get read, and feature requests that shape what gets built.
When a one-sentence test is no longer enough, the same engine runs on your machine with parameter sweeps, walk-forward optimization and Monte Carlo. If you are moving over from another library, Manifold-BT vs vectorbt is a good place to start.
A backtesting Discord vs a signals server
Search for a trading Discord and most of what comes back is signal groups. They answer a different question.
| Manifold-BT Discord | Typical signals group | |
|---|---|---|
| What you come for | Testing your own ideas | Someone else's trade calls |
| What you get | Backtests, code help, method | Alerts, picks, entries |
| Where the edge is | Evidence you can rerun | Trust in the caller |
| What it costs | Nothing to join | Often a monthly subscription |
Questions about the Discord
Bring a strategy you want to test
Join the server or add Fold to your own, type /backtest, and see what your idea did on years of history. When you want more, the engine is one pip install away.